Friday, April 8, 2011

A Little Bit of Looking at the Data

Today the Daily Mail is again talking about how the UK was on the edge of an economic apocalypse before George Osborne saved the day! Some things never change.

What would be more interesting would be to actually look at the economic data beneath the political and journalistic hyperbole, wouldn't it?

I'm writing up some long overdue notes for some lectures I did on fiscal policy, and I figured I'd just have a little look at the government deficit in the context of real GDP growth in the UK over the past 30 years. Here's what the two data series look like:
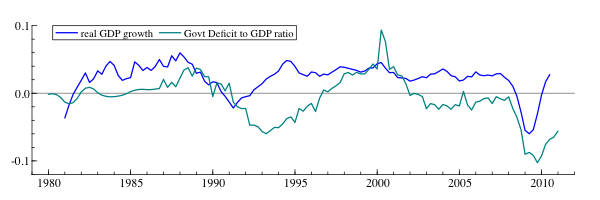
The government deficit to GDP ratio, and real GDP growth

Why am I doing this? Well because when an economy enters a recession, things economists call automatic stabilisers kick in: Benefits are paid to people made unemployed, and income and corporation tax receipts fall since less profits are made and less income is earned. These two effects will make a budget deficit worse regardless of how profligate a government is, so long as it provides unemployment benefits, and runs an income and corporation tax system.

So what about the biggest recession in 70 years kicking in? Surely that's going to have quite an impact on government finances, right? Looking at the two series above, we can see that indeed the recession we just emerged from was deeper than anything since 1980, and indeed the government deficit was also deeper. It's interesting to note the 1992 recession, post-ERM. After that, there is quite a large budget deficit for quite a while. Interestingly enough, that deficit only becomes a surplus after 1997.

However, we should really think about taking the data seriously, shouldn't we? Eyeballing only gets one so far. Now both series are probably stationary (econometric speak), but clearly show persistence - GDP growth is strong for a while, then weak, deficits tend to hang around like bad stains. So we should think about a dynamic econometric model. The real beauty of such models (say, an Autoregressive Distributed Lag model) is that we can let the data tell us about the long run solution, or error correction reformulation as it's called in the linked paper. This is the long-run relationship between the two variables: So if real GDP growth is at its expected value, what do we expect the deficit to be?

This way we can say: How far out of equilibrium are we right now, compared to economic history? I'm not going to bore anyone with the details (email me if you'd like them, I'm more than delighted to provide), but of course it's fascinating to look at something like this and see just how much we are currently teetering on the brink. The red line in the following diagram shows us exactly how far out of equilibrium we are currently:
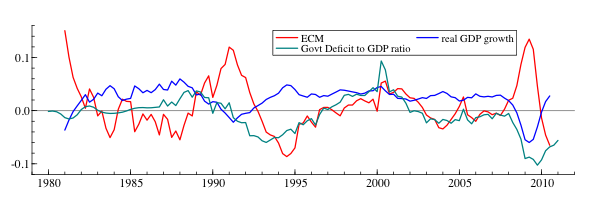
Fiscal Equilibrium in the UK

The deficit and real GDP growth are also plotted there still. The red line is equilibrium, or how much too high or too low is the deficit given the state of the economy. The important thing is that this is estimated over real data, and it should also be said that this is data starting in 1981, so 16 years of a Conservative government then followed by 13 years of Labour - it's a nice mix of the two.

So we see the impact of the financial crisis with a big positive movement which looks bad, right? That is until you realise that this is saying that the deficit was not large enough given the size of the contraction in real GDP! Calculations, based on the data, says that at the height of the recession, when real GDP contracted at 6%, the correct deficit given past UK economic history (16 years of Conservatives), excluding all economic theories, the deficit should have been an eye-watering 22% of GDP, not the trifling 9% it was at this point (2009Q2). Only as we entered 2010 did the equilibrium relationship (called ECM) turn negative, suggesting the deficit is too high now, and even by 2010Q3 it had not reached the depths of disequilibrium (a deficit too high) it reached in 1994.

Interesting stuff. Are we teetering on the brink of an economic apocalypse? Were Labour reckless with public finances? Not if you consider economic data taking into account Conservative policies between 1981 and 1997, at any rate.

Tuesday, April 5, 2011

The Alternative Letter

We've recently covered monetary policy, and the current UK framework where the Bank of England has been granted independence from political interference to use tools of monetary policy (interest rates and QE amongst others) to achieve an inflation target. We noted in lectures that for a long time now, the Bank has missed the target and we have inflation over 4% (target 2%).

In Money Week there's a mock alternative response from the Chancellor; if inflation misses the target, the governor of the Bank writes a letter to the Chancellor, and the next day the Chancellor responds. The Chancellor usually refrains from being critical, and hence this has drawn criticism: Why shouldn't the Chancellor start holding the Governor to account?

The letter is of course highly sarcastic and tongue in cheek, but it is written for a reason and helps us think a little more about monetary policy and the current framework. It is essentially true that the Bank has no regulator: Nobody is really keeping check on whether the Bank hits the target or not. Osborne can't really do it, as the letter kind of hints at with its final riposte: Maybe we should find someone else to do the job if you can't Mervyn (paraphrasing). If Osborne wrote a letter like this, it would be a very clear indication that the Bank's independence was no longer. If the Bank did subsequently raise rates, regardless of why it did so, it would be easily interpreted as having done so under political pressure. And if political pressure starts once again to dictate what happens with interest rates, then we're right back to square one, where we were before 1997 and the political business cycle.

The letter also makes some other important points:

  • Why are forecasts so bad?
  • How do we know inflation is caused by the weak exchange rate and not negative real interest rates and QE?

On the first, the stock answer is that the economy is a complicated beast. But the letter kind of hints at that when it criticises the reliance on the output gap in a rather Austrian-type criticism: How can we really know about this incredibly complicated and generally theoretical entity called the macroeconomy? Of course, just because something is complicated is no reason to give up on it, particularly when policy needs to be made (I'm not going into any arguments over free banking and the like).

On the second, the 30% fall in the trade-weighted exchange rate noted in lectures means that the goods we import (which is quite a few) are more expensive, and since these often take up a large portion of our basket, then it is quite reasonable to assert the high inflation is due to that - along with the VAT rise, since that also makes the goods we buy more expensive. Remember, inflation is just the change in the Consumer Price Index (CPI), year-on-year, for a given month, and the CPI is calculated over a "basket of goods" which is supposed to be representative of what the average person buys.

Wednesday, March 30, 2011

Correlation and Causality

We've now got through the course content for econ101b in lectures, so enjoy the vacation! I thought I'd link up an article by John B Taylor, who has recently become a staunch proponent of government austerity. He's supported/encouraged by Greg Mankiw, who is another Republican poster child.

For those more averse to all things US, the Republicans are much more right wing than any of the mainstream UK political parties, although their closest equivalent would be the Conservative Party.

John B. Taylor is the man who proposed the Taylor Rule, a rule that monetary policymakers should follow when setting monetary policy. He strongly believes the sole cause of the Financial Crisis was that monetary policy was too loose, according to his model (scroll through old posts on his blog and you'll get a sense of this, I can't find the original article).

In the main linked article though, Taylor takes us through some scatter plots. Now these are interesting scatter plots - they show that government purchases are positively correlated with unemployment, and that investment is negatively correlated. From this, Taylor draws the conclusion that austerity is fine and should be encouraged (since it means lower government purchases) while at the same time investment should be encouraged.

This is all well and good, but a scatter plot shows correlation and not causality. Why does this matter? Well, Taylor proposes austerity (cutting back government purchases drastically) because in his mind it will cause lower unemployment. But what if the causality is the other way? What if high unemployment causes higher government purchases? Now this is hardly controversial really, since if people become unemployed, the government will have more to do: Higher benefits, likely higher other costs too, and naturally we might see some attempt by government to stimulate the economy by increasing purchases (data is 1990 on). If this happens, the purchases happen at the same time as the unemployment exists, hence we get a correlation like in the plot.

So does Taylor's plot really tell us much? Even if the government purchases worked, this plot wouldn't tell us that since it's a dynamic picture - i.e. the reduction in unemployment wouldn't necessarily come instantaneously! So the plot has ignored causality and also the dynamic nature of cause and effect in the macroeconomy.

It's another example of why it's very hard to know who to trust when doing economics. Blogs are great - they contain the opinions of top economists who can comment on real world events as they are happening. But they are not what we call peer reviewed. For a paper to get into a journal, it must be read by a number of referees who decide on its quality. Shoddy data work like that shown in this blog post, would not get past the referees and editors at a top journal.

The conclusion to draw - be careful, and in particular if you do read blogs (and I'd recommend it!) try to read a balanced selection of them - something like the list given on the right-hand side of this blog.

Thursday, March 24, 2011

The Budget

Yesterday George Osborne gave his first full budget, and in reality it did not change a lot. There is much commentary all around, but often the best place to go to for informative and balanced comment is the Institute for Fiscal Studies. A little look at their track record over time shows they are happy to criticise whichever party is in government. Here is their take on yesterday's budget. Well recommended. And enjoy that extra penny off each litre when you fill up next...


Tuesday, March 15, 2011

Superfreakonomics in Birmingham

I'm sure publicity for this will pick up in time, these guys are not shy by any stretch of the imagination, nor do they miss a money-making promotion opportunity. Stephen Dubner is in Birmingham on 20 June promoting his book with the economist Steven Levitt, Superfreakonomics, the "freakquel" to Freakonomics.

I'm quite sure it'll be a very entertaining show and if you're interested in pursuing economics further, and you're in Birmingham in June (or Brighton, Liverpool or Cambridge), then it will be worth your while getting along!

Monday, March 14, 2011

Monetary and Fiscal Policy

This week and next week we'll talk about monetary and fiscal policy.  I put up the link last week of the interview with Mervyn King, governor of the Bank of England, which contained his views on how monetary policy saved the economy from the abyss during the recession in 2008-09.  Equivalently, politicians and many economists argue that fiscal policy can have an impact on growth - but that impact is complex, as we'll find out.  Nonetheless, Labour have today started talking about their proposals for growth, ahead of next week's Budget.

Changes to fiscal policy (how the government spends and taxes) are bound to have an impact on the economy; you learnt in econ101a how taxing wages distorts incentives in markets, and this is the same in goods markets too.  Hence governments are able to influence economic activity in dramatic ways.  In econ101b we'll look a little more at this at the macro level, thinking about government spending as an aggregate and how that can influence economic activity.

Monday, March 7, 2011

Mervyn King Interview

Quite soon we'll start to look in quite a bit of detail at monetary policy.  Here's an interview in the Torygraph Telegraph with the Governor of the Bank of England, Mervyn King, which is very interesting reading.